Laid Off at 61: Can a $900/Month Delivery Gig Save Denise's Retirement?
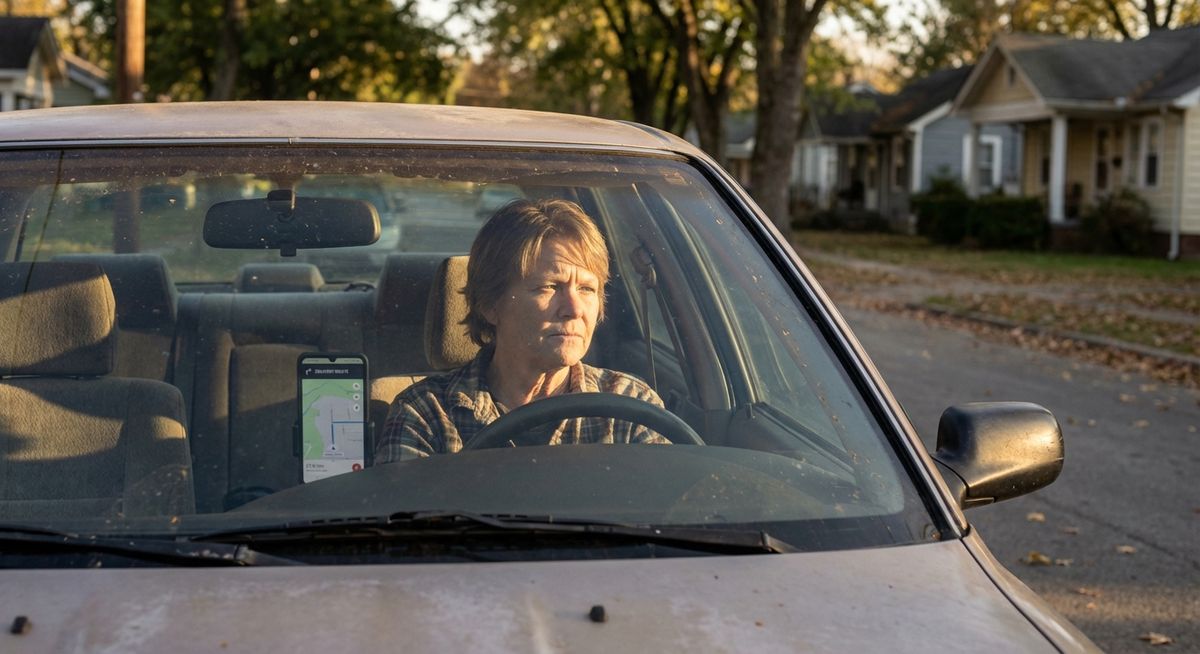
Denise didn't plan to retire at 61. After 22 years as an operations manager at a regional packaging company in Knoxville, Tennessee, a corporate restructuring made the decision for her. Now she's facing a retirement planning challenge that hits way harder when you didn't choose the timing: with $367,409 in savings, a small pension, and Social Security still six years away, can she actually make this work?
- Portfolio: $367,409 at age 61, depleted by age 76 even with gig income through 65
- The gap: Six years with only a $600/month pension before Social Security kicks in at 67
- Gig income: $900/month slows the bleeding but doesn't close the gap alone
- Real answer: Stack multiple small moves: trim spending, optimize Social Security timing, consider downsizing, use the low-income window for Roth conversions
The situation is serious but not hopeless. Several strategic adjustments, made soon, could meaningfully change the outcome.
The Retirement Plan at a Glance
Here are the key assumptions driving the retirement projection:
| Parameter | Value |
|---|---|
| Current Age | 61 |
| Retirement Age | 61 (involuntary) |
| Plan Horizon | Ages 61 through 89 |
| Monthly Spending | $3,800 (today's dollars) |
| Starting Portfolio | $367,409 |
| Portfolio Allocation | 50% stocks / 50% bonds |
| Expected Equity Return | 7% |
| Expected Fixed Income Return | 4% |
| Inflation Assumption | 3% |
| Social Security | $21,600/yr starting at age 67 |
| Pension | $7,200/yr starting now |
| Filing Status | Single |
That paid-off home is a real asset here. No mortgage payment keeps monthly spending lower than a lot of retirees face. But $3,800 a month still adds up to $45,600 a year, and without a paycheck, that money has to come from somewhere.
About This Simulation
The projection below already includes the $900/month gig income from 61 through 65, plus the pension and Social Security at 67. Even with the gig, the portfolio runs out at 76.
Six Years in the Desert: The Pre-Social Security Gap
The hardest stretch in this plan isn't the 70s or 80s. It's right now. Ages 61 through 67, the gap between losing a job and collecting Social Security.
During these six years, the only guaranteed income is a $7,200 annual pension from a manufacturing firm where Denise worked about a decade earlier. That's $600 a month. Against $3,800 in monthly spending, she's short $3,200 every single month. That means roughly $38,400 a year has to come straight from the portfolio just to keep the lights on and the property taxes paid.
This early draw-down period is where sequence of returns risk becomes a retirement killer. Heavy withdrawals in the first few years, especially during a market downturn, can permanently damage a portfolio's ability to recover.
Withdrawal Rate Reality Check
At $38,400 a year from a $367,409 portfolio, the withdrawal rate is 10.5%. Even with gig income reducing that to 7.5%, both figures are well above the 4% threshold most financial planners consider sustainable.
This is where the delivery driving enters the picture. At $900 a month ($10,800 a year), gig work would cut annual portfolio withdrawals from $38,400 to around $27,600. That's meaningful. It's the difference between draining savings at a 10.5% annual rate and draining them at a 7.5% rate.
But here's the uncomfortable truth. Even 7.5% is well above what most financial planners consider sustainable. The "4% rule," based on William Bengen's landmark 1994 research and later validated by the Trinity Study, exists for a reason. In fact, there's a growing case that the traditional 4% rule is broken in today's environment. At nearly double that threshold from day one, this plan is under serious stress.
Run your own version of this plan
See your own projections, charts, and what-if scenarios on ReadyAimRetire.
Build Your Own PlanWhat the Portfolio Analysis Shows
The projection (with gig income through 65) tells a clear story in three acts.
Act One: The Draw-Down (Ages 61 to 67)
The portfolio drops steadily as it funds the gap between the pension and spending needs. By the time Social Security kicks in at 67, a big chunk of the nest egg is already gone. The 50/50 stock-bond allocation provides some growth (a blended 5.5% nominal return), but not enough to offset withdrawals of this size.
Act Two: The Reprieve (Ages 67 to mid-70s)
Social Security at $21,600 a year ($1,800/month) totally transforms the cash flow picture. Combined with the $600/month pension, that's $2,400 in guaranteed monthly income. Portfolio withdrawals drop dramatically, and for a few years, the math feels almost manageable.
Act Three: The Depletion (Mid-70s to 76)
And then inflation shows up. At 3% annually, that $45,600 in today's spending keeps growing in nominal dollars. Social Security does get cost-of-living adjustments, but those are calculated using the CPI-W, an index based on working-age household spending. It underweights healthcare and overweights categories like transportation relative to what retirees actually spend. Healthcare inflation alone has averaged roughly 5.8% annually, well above typical COLA increases. The portfolio, now much smaller after six years of heavy withdrawals, just can't keep pace. At age 76, the money runs out.
The situation is serious, but it's not hopeless. Not even close. She's already shown she's willing to put in the work. Now it's about making sure that work is pointed in the right direction.
The Final Years (Ages 76 to 89)
With no portfolio remaining, the plan relies entirely on Social Security and the pension. Depending on inflation-adjusted values, that could mean a sharp reduction in standard of living for the remaining 13 years of the projection.
The bottom line: the baseline plan depletes the portfolio at 76. Ending net worth is $0. Total lifetime taxes come to approximately $130,090, with an average effective rate of 7%.
The Gig Work Question, Answered Honestly
So back to the central question: can $900 a month in delivery driving save this retirement?
The honest answer is no, not by itself. But it's not pointless either. Not even close.
The gig income does three concrete things:
- It reduces the burn rate. Dropping from a 10.5% withdrawal rate to 7.5% is already baked into the age-76 result; without it, the money would run out sooner.
- It keeps a person active and engaged during a period when involuntary retirement can take a real psychological toll. Having somewhere to be and something to do matters more than the paycheck sometimes.
- It provides optionality. Increasing hours during high-demand periods like holidays, weekends, and bad weather could push delivery income closer to $1,200 or $1,500 a month, which changes the math further.
But gig work has real costs that need accounting. Vehicle depreciation, gas, maintenance, and self-employment taxes (15.3% on net earnings for Social Security and Medicare taxes, plus income tax) all eat into that $900. After expenses, the net might be closer to $600 or $650. And this kind of work has a physical shelf life. Driving for a delivery app at 61 is one thing. Doing it at 68 or 70, with the bending, lifting, and long hours in the car? That's another conversation entirely.
So the simulation, which already includes the gig income through 65, shows that gig work alone doesn't close the gap. It slows the bleeding. To actually change the outcome, it needs to be combined with other moves.
What Could Actually Move the Needle
Here's where I get a little more optimistic. Several strategic adjustments could meaningfully improve this trajectory. None of them are painless, but all of them are worth modeling.
Cut Spending
This is the most powerful lever available. Full stop. The $3,800 monthly budget is reasonable for Knoxville, but trimming it to $3,200 or even $3,000 compounds dramatically over a plan that spans nearly three decades. Cooking more, dropping subscriptions, shopping strategically. Even $400 a month in savings extends the portfolio's life by years. Every dollar not spent is a dollar that stays invested and continues to grow. For a deeper look at making those early dollars stretch, check out our guide on budgeting smart in the first five years of retirement.
Delay Social Security
This one feels counterintuitive when money is tight, but hear me out. The current plan has Social Security starting at 67, which is full retirement age for anyone born in 1960 or later. Pushing that to 70 would increase the annual benefit by 24%, from $21,600 to roughly $26,784, thanks to delayed retirement credits of 8% per year. The tradeoff is three more years of portfolio withdrawals, which is painful in the short term. But the higher guaranteed income for the rest of her life could be the difference between running out of money in her mid-70s and making it significantly further.
Consider the House
A paid-off home is a tremendous asset that doesn't show up in the portfolio balance. But a three-bedroom house in Knoxville for a single person is more house than necessary. Downsizing to a smaller home or a condo could free up cash while reducing property taxes, maintenance, and utility costs. It doesn't have to happen tomorrow, but it belongs in the conversation.
Rethink the Allocation
A 50/50 stock-bond split is conservative for someone who needs this money to last through age 89. At 61, the time horizon is still long. Shifting to 60/40 or even 65/35 in favor of equities introduces more short-term volatility but historically produces better long-term growth. The difference between a blended 5.5% return and a 6.0% or 6.5% return compounds significantly over three decades.
Explore Part-Time W-2 Work
Gig work is flexible, but traditional part-time employment might offer something delivery apps can't: employer-subsidized health insurance. Healthcare is one of the biggest expenses for early retirees, and a part-time position with benefits can bridge both the income and insurance gap in retail, warehousing, or administrative work.
Ready to run your own numbers?
See how your retirement plan stacks up with ReadyAimRetire's free retirement calculator.
Try It FreeThe Healthcare Factor
One number that's conspicuously absent from this plan is healthcare spending. And this is where forced early retirement at 61 gets particularly expensive. Medicare eligibility doesn't begin until 65, leaving four years of coverage to fund independently.
ACA marketplace coverage for a 61-year-old in Tennessee is not cheap. The enhanced premium tax credits that kept marketplace plans more affordable expired at the end of 2025. Without subsidies, a benchmark silver plan for a 61-year-old now runs roughly $1,200 to $1,400 per month in many Tennessee markets. With income-based subsidies (which low gig income may actually help qualify for), the cost could come down to $500 to $800 per month, but eligibility depends on total household income and varies by county.
If healthcare costs are already baked into the $3,800 monthly budget, this is being managed. If they're not, actual spending needs are higher than the plan reflects, and that would accelerate the depletion timeline.
Once Denise does hit 65, choosing the right Medicare supplement plan becomes its own high-stakes decision. The $3,800 figure should be verified against actual expenses, with healthcare explicitly accounted for in the years before and after Medicare.
The Roth Conversion Opportunity
Here's a detail I want to flag because it's one of those things that's easy to overlook: there's no Roth IRA in this plan. With income temporarily low (just the pension and gig earnings), the current tax bracket is likely very favorable. This creates a window for Roth conversions, meaning you move money from a traditional IRA or 401(k) into a Roth, pay taxes at today's low rate, and let the converted funds grow tax-free.
Roth Conversion Window
There are no income limits on Roth conversions (unlike Roth contributions, which phase out at higher incomes). The strategy: "fill up" the lower tax brackets each year with conversion amounts, staying below the threshold where the tax cost outweighs the benefit. We've written a full breakdown of when and how to convert for maximum benefit.
Once Social Security kicks in at 67, taxable income rises and this window narrows. The years between 61 and 67, the same years that feel most financially stressful, are paradoxically the best years for tax-efficient repositioning. A few strategic conversions now could reduce the tax burden in later years and provide more flexibility in how and when savings get drawn down.
Where Things Stand
This is a story about someone doing what resourceful people do when the plan falls apart: improvising. The delivery gig, the coupon clipping, the self-reliance. Those instincts are sound. But instinct alone doesn't solve a math problem, and the math right now says the portfolio runs out at 76 with 13 years of life expectancy still on the clock.
The good news is that there are more options here than might be obvious at first. A paid-off home. Low taxes. A pension that, while small, provides a floor. Time to make Roth conversions before Social Security changes the tax picture. And a willingness to work, which honestly counts for more than any single financial strategy.
Action Steps for Denise's Situation
- Keep driving, but track the real numbers. Log mileage, gas, maintenance, and net income after self-employment taxes. Know exactly what that $900 is really worth.
- Trim $400 to $600/month from the budget. Even small cuts compound dramatically over a 29-year plan horizon. Every dollar saved is a dollar that stays invested.
- Model delaying Social Security to 70. The 24% increase in guaranteed lifetime income could be the single most impactful move available.
- Start Roth conversions now. The low-income window between 61 and 67 is the best time for tax-efficient repositioning. Don't waste it.
- Explore part-time W-2 work with benefits. Employer-subsidized health insurance alone could save $500+ per month before Medicare kicks in at 65.
- Put downsizing on the table. A three-bedroom house for one person is more house than necessary. Freeing up equity while cutting property taxes and maintenance changes the math.
The path forward isn't really about whether $900 a month in delivery income "saves" retirement. It's about stacking multiple small moves. Trimming spending, optimizing Social Security timing, considering the housing situation, and using this low-income window for tax planning. No single adjustment fixes a plan that's burning through savings at 7.5% a year. But four or five adjustments, made deliberately and soon, could genuinely change the ending.
Want to see how adjustments like these affect the numbers? You can build a plan like this one, adjust the assumptions, and test your own scenarios at ReadyAimRetire.
See your own interactive projections, charts, and settings on ReadyAimRetire.